The Rate You See Is Rarely the Rate You Get
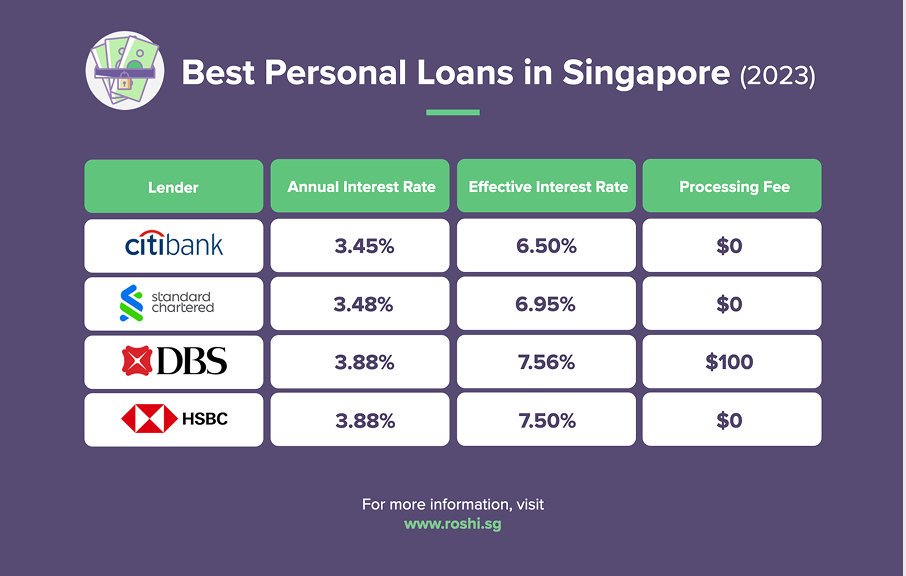
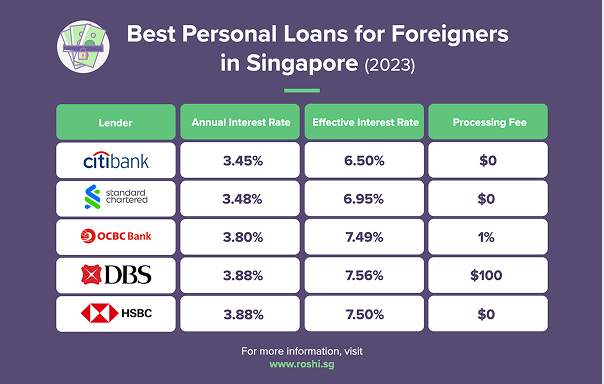
Advertised rates like "from 1.08% p.a." are best case scenarios for top tier applicants with excellent credit scores, high income and existing relationships with the bank.
Most borrowers receive rates of 5% to 12% EIR depending on their credit profile. When using this calculator, run scenarios at multiple rates, the advertised rate, a mid-range estimate 7% to 8% EIR) and a conservative estimate 10% to 12% EIR) to understand the realistic range of monthly repayments before applying.


How Tenure Affects Total Cost
| Loan Amount | 2 Years (EIR 8%) | 3 Years (EIR 8%) | 5 Years (EIR 8%) |
|---|---|---|---|
| $10,000 | $453 per month = $872 interest | $313 per month = $1,268 interest | $203 per month = $2,180 interest |
| $20,000 | $905 per month = $1,720 interest | $626 per month = $2,536 interest | $406 per month = $4,360 interest |
| $30,000 | $1,358 per month = $2,592 interest | $939 per month = $3,804 interest | $608 per month = $6,480 interest |
| $50,000 | $2,263 per month = $4,312 interest | $1,565 per month = $6,340 interest | $1,014 per month = $10,840 interest |
When to Use This Calculator
Interest Rate Trends
Research updated on 8 Sep 2026 - September 2026 hasnt changed the usefulness of personal loan calculators for Singapore borrowers. The underlying rates are still the same as August which means calculator estimates remain accurate for planning purposes.
Licensed moneylenders are still charging around 3.8% per month on average with the 4% cap, 10% admin fee and S$60 late fee unchanged. Banks continue offering personal loans from around 2.5% effective p.a. for qualified borrowers. A calculator helps you see how these different rate structures affect monthly repayments and total cost before you commit.
Demand for calculator tools remains steady as borrowers become more careful about affordability. With living costs still high in Singapore, more people want to know exactly what their monthly commitment will be before filling out an application.
Licensed moneylenders in Singapore are still operating at around 3.8% per month as of September 2026. When using a personal loan calculator to estimate repayments for a licensed moneylender loan, borrowers should input the 3.8% monthly rate and remember to add the 10% admin fee to the total cost.
For example, a S$3,000 loan at 3.8% per month over six months would have a principal of S$3,000 plus an admin fee of up to S$300. The calculator should reflect both the monthly interest and the upfront fee to give an accurate picture of total repayment.
Most licensed moneylender websites now include their own calculators but Thanh recommends cross-checking with an independent tool. Some lender calculators only show the monthly instalment without clearly displaying the admin fee or total interest paid over the full tenure.
Banks in Singapore offer personal loan calculators on their websites to help borrowers estimate monthly repayments before applying. As of September 2026, these calculators reflect current promotional rates which can be as low as 2.5% effective p.a. for well-qualified applicants.
A bank personal loan calculator typically lets you input the loan amount, tenure and estimated interest rate to show monthly instalments and total interest cost. Some calculators also factor in processing fees. DBS, OCBC, UOB and Standard Chartered all provide these tools.
The key thing to remember is that calculator results are estimates. The actual rate you receive depends on your credit score, income level and existing debt. Banks usually display their lowest advertised rate in the calculator but your final offer may be higher. Use the calculator as a planning tool, not a guarantee.
In September 2026 bank personal loan rates range from 0.90% p.a. to 1.48% p.a. while licensed moneylenders charge ~3.8% monthly. When you use a calculator test both scenarios side by side. A S$10,000 bank loan at 1.00% p.a. over 3 years costs roughly S$280 per month. The same amount from a moneylender at 3.8% monthly costs roughly S$380 per month. That is S$100 per month difference.
Do not just look at the monthly instalment. Look at the total interest paid over the full tenure. With rates this low at banks extending the tenure to reduce monthly pressure may not be necessary.
Use the calculator to find the shortest comfortable tenure not the longest possible one. Every month you shave off saves interest and with bank rates at 5-year lows now is the time to be aggressive about repayment by Trinh Thanh.
For borrowers using personal loan calculators in September 2026, the tool is only as good as the information you put in. Use realistic interest rates rather than the lowest advertised figure. If your credit score is average, you will not get the banks best promotional rate.
Compare total repayment cost, not just monthly instalments. A lower monthly payment over a longer tenure often costs more in total interest. Use the calculator to find the sweet spot where the monthly amount is manageable and the total cost is minimised.
Remember that calculators do not include late fees or early repayment penalties. Read the full loan terms after getting a preliminary quote. The calculator gives you the starting point. The actual agreement gives you the real numbers.